I live and work in Ballarat. If you would rather sit down with someone than deal with a call centre, that is what this is. If you would rather do it all by phone and email, that works too.
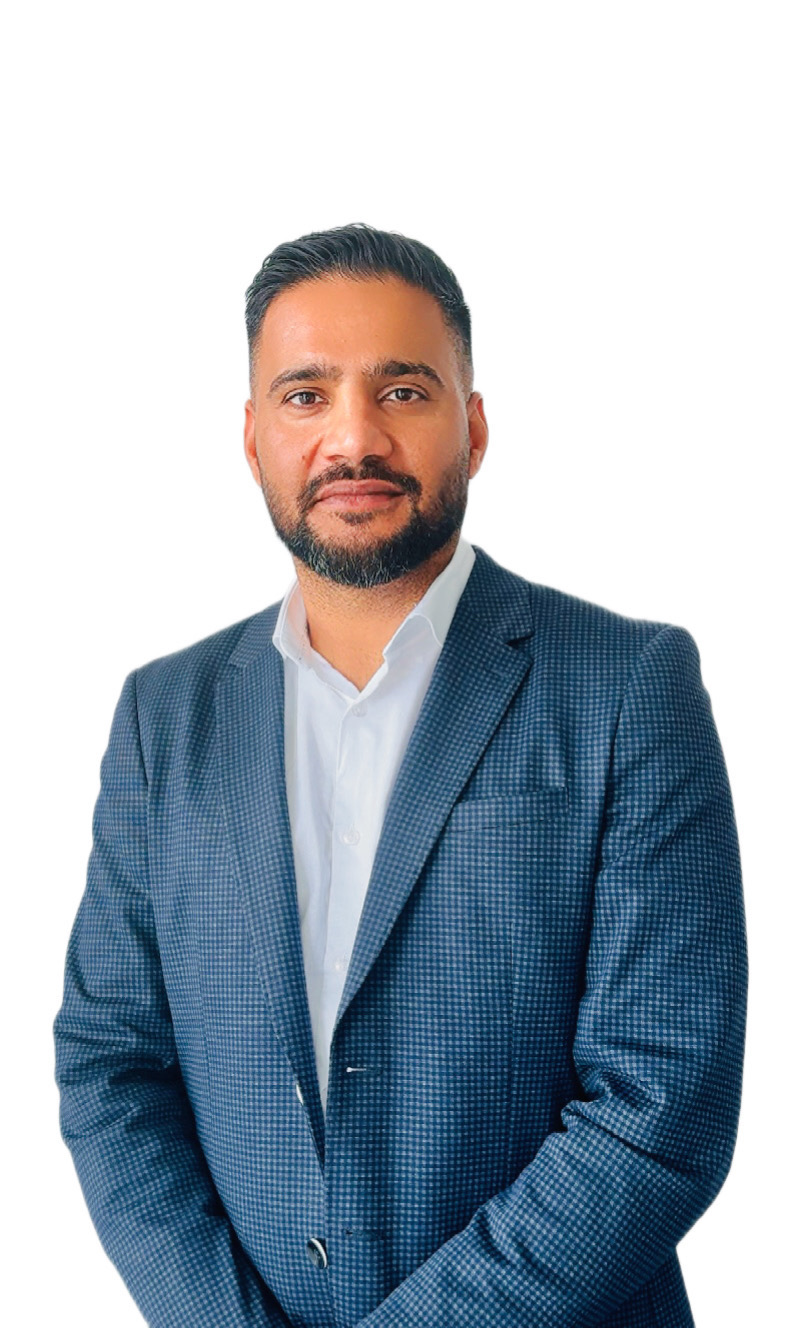
Aman Sidhu, Blissful Wealth
A lot of home lending does not require anyone to be in the same room. Documents are shared securely, applications are lodged electronically, and most of the process runs on phone and video regardless of who you deal with.
So it is worth being honest about where local actually matters.
That last one is where most national advice quietly gets it wrong for Ballarat buyers.
The First Home Guarantee lets eligible first home buyers borrow with a deposit as low as 5% without paying lenders mortgage insurance. From 1 October 2025 there are no income caps and no limit on places, which removed two of the barriers people used to run into.
What remains is the property price cap, and it is not one number.
The cap is $950,000 for Melbourne and Geelong. For the rest of Victoria, including Ballarat, it is $650,000.
Most national articles quote the metropolitan figure because that is where most of their readers are. If you are buying in Ballarat and working to $950,000, you may be looking at properties that would put the scheme out of reach without realising it.
Given where Ballarat prices sit, that $650,000 cap is a real constraint rather than a technicality. It is worth knowing before you start looking, not after you have found something.
A large share of what happens here is new builds, particularly in the growth areas on the western and southern edges of the city. House and land packages, and buying land then building on it, are common.
Construction lending works differently from a standard home loan. Funds are released in stages, your repayments climb as the build progresses, and you generally have to spend your own contribution before the lender releases anything. Your building contract matters more than most people expect.
I have been through a build myself, and I have since taken clients through the same process. If building is on your list, the construction loan guide covers how it actually works.
First home buyers
Deposit, schemes, concessions, and the costs nobody mentions.
Building a home
How construction loans actually work, stage by stage.
Refinancing
Whether moving is genuinely worth it once costs are counted.
Property investors
How structure affects what you can do next.
Self-employed
Add-backs, company structures, and how lenders read your financials.
“I had a very tricky case with an investment property and a car loan, which made it hard to get a land loan. But Aman handled everything so well and got my loan approved! They were very patient, explained things clearly, and always kept me updated.”
Ankith · Construction loan
“We recently refinanced our mortgage with Blissful Wealth, and I was amazed at how smooth and hassle-free the experience was! From our first call, Aman guided us with clarity and ensured we fully understood each step.”
Taimur · Refinance
Reviews reflect individual client experience and are published as written. They are not a guarantee of any particular outcome. Every situation is assessed on its own merits.
I am based here, and plenty of my work is local. But consumer home lending is regulated under a single national credit law, and my licence covers every state and territory, so where you live does not determine whether I can help you.
What does change between states is the government side of a purchase. Stamp duty, first home buyer grants and concessions differ everywhere, and those differences are part of the conversation from the start rather than something discovered late.
If you are early, that is a good time rather than a premature one. Most of what determines your outcome is settled well before you find a property, and almost none of it can be fixed in the week before you make an offer.
No pressure and no obligation. Just a clear picture of your position and your realistic options.
Talk about your optionsOr try the readiness toolAman Sidhu is a Credit Representative (Credit Representative Number 555735) of Purple Circle Financial Services Pty Ltd, Australian Credit Licence 486112.
Information on this website is general in nature and does not take into account your objectives, financial situation or needs. It is not credit assistance or a recommendation to apply for any particular product. Your full financial situation and requirements need to be reviewed prior to any offer or acceptance of a loan product.
Know where you stand. Know your options. Move with confidence. Based in Ballarat, working with clients across Australia.
Aman Sidhu is a Credit Representative (Credit Representative Number 555735) of Purple Circle Financial Services Pty Ltd ABN 21 611 305 170, Australian Credit Licence 486112. MFAA member 578479.
Information on this website is general in nature and does not take into account your objectives, financial situation or needs. It is not credit assistance or a recommendation to apply for any particular product. Your full financial situation and requirements need to be reviewed prior to any offer or acceptance of a loan product.