The hardest part of buying our first home wasn't saving the deposit. It was not knowing what I didn't know.
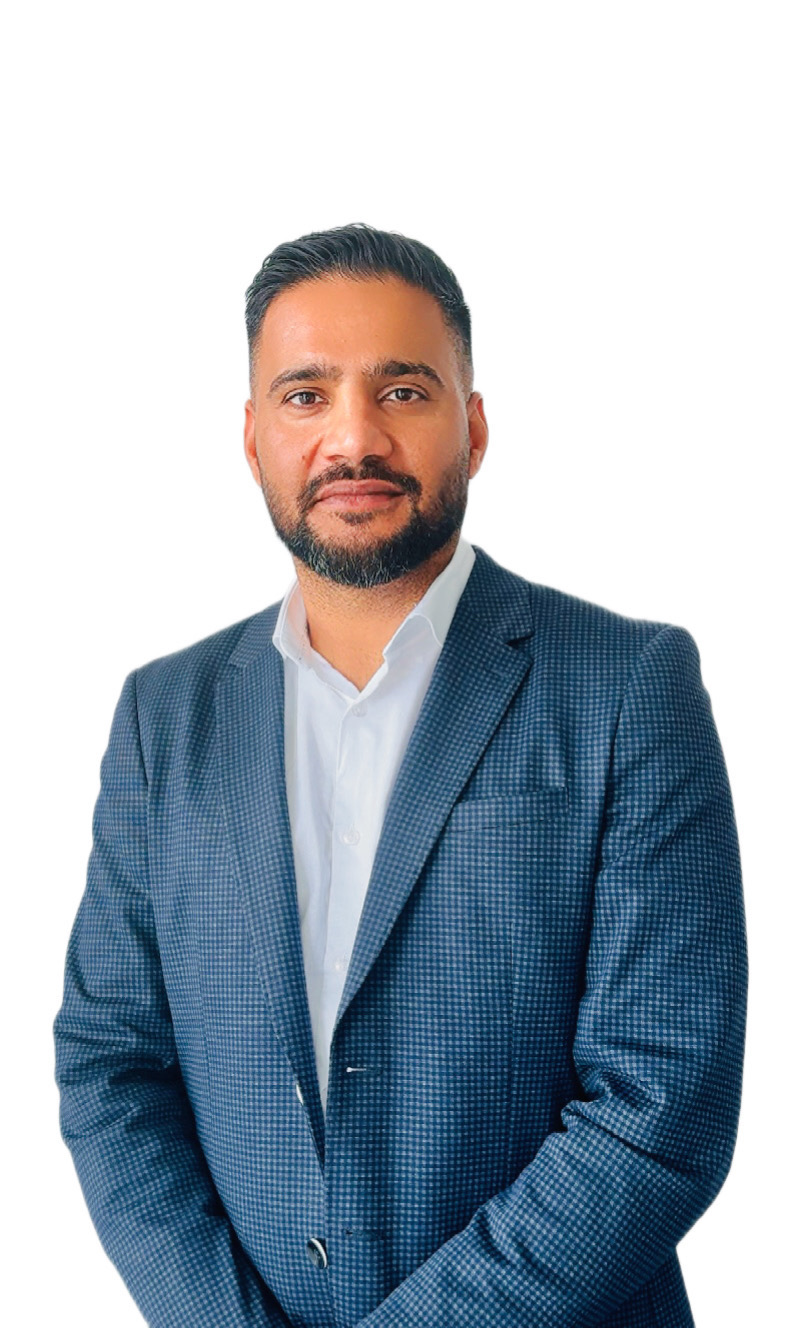
For ten years I worked in the university sector. Then my wife and I got married, started a family, and needed a place of our own.
That's when I found out how much I didn't know.
Stamp duty concessions. The First Home Owner Grant. Which lender to go to, and why it mattered. Which loan features were genuinely useful and which were noise. How a construction loan actually works, and how different it is from a standard home loan. Contracts. Conveyancers. Builders. Developers.
Every step raised another question. Most of the answers I found were either too general to help, or written by someone trying to sell me something.
We got there in the end, and moved into a home we'd built. But I kept coming back to the same thought: none of that needed to be as stressful as it was. What was missing wasn't effort. It was someone who could explain the whole picture instead of one piece of it.
So in 2022 I left my university career to learn this industry properly.
I started with the Certificate IV in Finance and Mortgage Broking. I spent time working inside a major Australian bank, because I wanted to understand home lending from the lender's side of the desk: how applications are actually assessed, not how they're advertised. I then worked at a large financial services firm in superannuation and investments, which changed the way I look at property. It stopped being a purchase and started being one part of a much bigger financial position.
I completed the Diploma of Finance and Mortgage Broking Management, and started Blissful Wealth in early 2024.
Understand the position. Understand the options. Then make the decision.
A lot of home loan conversations start with the wrong question: "which bank should I go to?" That question can't be answered properly until we understand where you actually stand.
So I start with your position: your income and how a lender is likely to read it, your deposit or equity, your timeline, and what you're actually trying to do. Then we look at what's realistically available, and where the trade-offs and limitations sit. Then you decide.
You should walk away from our first conversation knowing more about your own position than when you started.
The question is almost never "which loan." It's "are we even close?" And then, once you are, which concessions and schemes you actually qualify for, whether it's better to buy established or build, and how much of your deposit is going to disappear into costs you didn't know about.
I've been on the other side of this. I know which parts are genuinely complicated and which parts just feel complicated because nobody has explained them in order.
A construction loan doesn't work like a standard home loan, and most people find that out after they've already committed.
The money isn't advanced in one lump. It's typically released in stages as your builder finishes them, so what you owe changes as the build progresses. You're usually paying interest on what's been drawn while still paying rent or an existing mortgage. Lenders generally assess the property on what it's expected to be worth once complete, based on your plans and a fixed-price building contract, which makes that contract and its specifications far more important than most people realise. Variations partway through a build can create complications nobody warned you about.
I've built, and I've since taken clients through the same process. That means I know which questions need asking before you sign a contract rather than after, when the answers start costing money. Progress payments, contract variations, how a valuer treats plans that haven't been built yet: none of that is abstract to me.
Most people don't refinance because they want a new loan. They refinance because something changed: a fixed rate ending, income moving, a renovation to fund, or a growing sense that the loan they signed four years ago no longer fits.
The useful work here isn't finding a lower number. It's working out whether moving is actually worth it once costs, structure and your plans for the next few years are accounted for.
I look at investment lending as an investor, not just as a broker. Experience in superannuation and investments trained me to read a property purchase as one line in a much larger financial position: how the structure affects what you can do next, how existing debt gets read by the next lender, and what a purchase closes off as well as what it opens up.
That's usually the part that gets skipped when the only question being asked is whether one loan gets approved.
Sole traders and company directors get judged on paperwork that was prepared for a completely different purpose: tax returns written to manage tax, not to demonstrate borrowing capacity.
The work is understanding how a lender is likely to read your financials, what may or may not be added back, how much history is needed, and often what timing would put you in a materially stronger position.
Blissful Wealth is based in Ballarat, Victoria. If you're looking for a local mortgage broker, that's what being local is genuinely useful for: meeting in person if you'd prefer to, understanding the area you're buying or building in, and knowing the Victorian stamp duty concessions and first home buyer schemes that apply here.
Beyond Ballarat, I work with clients throughout Victoria and across Australia. Consumer home lending is regulated under a single national credit law, and my licence covers every state and territory, so where you live doesn't determine whether I can help you. Most of the process runs on phone, video and secure document sharing, which is how a large share of home lending now works regardless of who you deal with.
What does change between states is the government side of a purchase. Stamp duty, first home buyer grants and concessions differ in every state and territory. Those differences are part of the conversation from the start, not something discovered late.
If you're self-employed, investing, or dealing with a situation that needs someone to actually work through the detail with you, distance is rarely the thing that matters.
No pressure, no obligation. Just a clear picture of your position and your options.
Talk About Your OptionsAman Sidhu is a Credit Representative (Credit Representative Number 555735) of Purple Circle Financial Services Pty Ltd, Australian Credit Licence 486112.
Information on this website is general in nature and does not take into account your objectives, financial situation or needs. It is not credit assistance or a recommendation to apply for any particular product. Your full financial situation and requirements need to be reviewed prior to any offer or acceptance of a loan product.
Know where you stand. Know your options. Move with confidence. Based in Ballarat, working with clients across Australia.
Aman Sidhu is a Credit Representative (Credit Representative Number 555735) of Purple Circle Financial Services Pty Ltd ABN 21 611 305 170, Australian Credit Licence 486112. MFAA member 578479.
Information on this website is general in nature and does not take into account your objectives, financial situation or needs. It is not credit assistance or a recommendation to apply for any particular product. Your full financial situation and requirements need to be reviewed prior to any offer or acceptance of a loan product.